How to Choose the Best Travel Insurance for Your Trip?
Choosing travel insurance is easier ↗ when I start with the trip instead of the insurance company. I first write down where I am going, how much money is non-refundable, what health coverage I already have abroad, who is traveling, and whether the itinerary includes activities or remote destinations. Only then do I compare policies.
I also do not treat the plan with the highest limits or the longest benefit list as automatically better. A useful policy should protect the financial risks that would genuinely matter on this specific trip without making me pay for protection I do not need. NAIC’s current 2026 guidance similarly recommends considering trip cost, destination, age, existing protection, and the risks a traveler wants to insure before buying.
For a beginner traveler, the goal is therefore not to find one company that is universally “best.” The goal is to find a policy whose coverage, limits, exclusions, deductible, eligibility rules, and price fit your trip better than the alternatives.
Travel insurance policies differ widely. Benefits that appear similar on comparison pages can have different covered reasons, exclusions, limits, definitions, and claim requirements. Always review the actual policy wording before buying.
Key Takeaways
- ✓Start with your trip risks before comparing insurance companies.
- ✓Calculate the amount of prepaid, non-refundable money you could actually lose.
- ✓Check existing health insurance before paying for additional overseas medical protection.
- ✓For U.S. travelers, Original Medicare generally provides very limited coverage outside the United States.
- ✓Compare medical evacuation separately from ordinary emergency medical coverage.
- ✓Destination and access to suitable medical care can change the level of protection you need.
- ✓Planned activities should be checked against policy exclusions.
- ✓Compare benefit limits, deductibles, and exclusions together.
- ✓Check whether coverage is primary or secondary where relevant.
- ✓Do not assume credit-card travel benefits replace a complete travel insurance policy.
- ✓Single-trip and annual policies serve different travel patterns.
- ✓CFAR can provide broader cancellation flexibility, but it normally costs more and has additional conditions.
- ✓NAIC currently says travel insurance commonly costs around 5%–10% of total trip price, but price varies by factors such as destination, age, season, and coverage.
- ✓The cheapest policy is not necessarily the best value.
- ✓The most expensive policy is not necessarily the best fit either.
There Is No Single “Best” Travel Insurance Policy
The word best can be misleading.
A policy that works very well for one traveler may be a poor fit for another.
Consider these trips:
Trip A
- ✓Four-day domestic trip
- ✓Refundable hotel
- ✓Low-cost flight
- ✓No unusual activities
Trip B
- ✓Three-week international trip
- ✓$8,000 in non-refundable bookings
- ✓Limited existing medical coverage abroad
- ✓Remote trekking
The insurance needs are clearly different.
A useful policy should match:
traveler + destination + money at risk + medical exposure + activities + trip structure.
That is the framework I use throughout the buying decision.
Step 1: Build a Simple Trip Risk Profile

Before opening insurance comparison sites, write down the basic facts.
I would record:
- ✓Destination
- ✓Trip dates
- ✓Number of travelers
- ✓Ages
- ✓Total trip cost
- ✓Non-refundable trip cost
- ✓Existing health insurance abroad
- ✓Planned activities
- ✓Remote destinations
- ✓Major cancellation concerns
- ✓Valuable belongings
This takes only a few minutes but prevents you from comparing policies without knowing what you actually need.
Start With the Money You Could Lose
Travel insurance is partly about transferring financial risk.
So I begin by asking:
If I had to cancel tomorrow, how much money would I actually lose?
Do not simply total everything you paid.
Separate:
- ✓Fully refundable costs
- ✓Partially refundable costs
- ✓Non-refundable costs
For example:
| Booking | Cost | Refundable? | Amount at Risk |
|---|---|---|---|
| Flight | $1,400 | No | $1,400 |
| Hotel | $2,000 | Yes | $0 |
| Tour | $800 | 50% | $400 |
| Train | $200 | No | $200 |
Total paid:
$4,400
Actual amount at risk:
$2,000
That $2,000 is more useful for cancellation planning than the total amount spent.
Do Not Buy Cancellation Protection Based Only on Total Trip Price
If most of your bookings are refundable, your cancellation exposure may be relatively small.
If nearly everything is prepaid and non-refundable, the situation is different.
This is why I separate:
trip price
from
financial loss if the trip does not happen.
For detailed covered reasons and exclusions, use Trip Cancellation Insurance Guide: What Is Covered and What Is Not? rather than choosing a plan based only on the cancellation percentage shown on a comparison page.
Step 2: Check What Insurance You Already Have
Before buying new insurance, I check existing protection.
You may already have some protection through:
- ✓Health insurance
- ✓Medicare-related coverage
- ✓Credit card
- ✓Homeowners or renters insurance
- ✓Airline or hotel refund policies
- ✓Employer benefits
- ✓Another travel policy
NAIC’s current guidance advises travelers to consider existing insurance before purchasing additional travel coverage because some protections can overlap.
The goal is to identify gaps.
Not to buy duplicate benefits blindly.
Existing Health Insurance Is One of the First Things to Check
For international travel, ask your normal health insurer:
- ✓Does my plan cover this country?
- ✓Does it cover emergency treatment?
- ✓What deductible applies?
- ✓Is overseas care treated differently?
- ✓Do I pay upfront?
- ✓How do I submit an international claim?
- ✓Does it cover medical evacuation?
The State Department advises travelers to determine whether their health insurance works abroad and to consider additional medical and evacuation insurance when protection is insufficient.
“Covered Abroad” Is Not a Complete Answer
If your insurer says:
“Yes, you are covered internationally.”
ask more questions.
You still need to know:
- ✓Coverage limit
- ✓Deductible
- ✓Network rules
- ✓Reimbursement process
- ✓Emergency-only restrictions
- ✓Evacuation coverage
A broad yes can hide important gaps.
For the deeper medical comparison, use Travel Medical Insurance Guide for International Travelers.
Medicare Travelers Need an Extra Check
For U.S. travelers, Medicare deserves specific attention.
Medicare’s current guidance says Original Medicare generally has very limited coverage outside the United States, although limited exceptions exist. Some Medigap policies can provide foreign travel emergency benefits, and Medicare Advantage plans can vary.
So if Medicare is your main domestic health coverage, do not assume it follows you worldwide.
Check the exact plan before comparing travel medical policies.
Step 3: Consider the Destination

The same policy does not create equal value everywhere.
I ask:
- ✓Is healthcare expensive?
- ✓Is suitable medical care easy to reach?
- ✓Will I spend time in remote areas?
- ✓Could evacuation become necessary?
- ✓Are any special risks relevant to the destination?
The State Department advises travelers to consider medical evacuation insurance because normal health plans often do not pay for air ambulance transportation back to the United States. It currently estimates such evacuation can cost about $20,000–$200,000, depending on location and medical condition.
That makes destination a serious insurance factor.
City Trips and Remote Trips Create Different Risks
Compare:
Major City Trip
- ✓Hospitals nearby
- ✓Easy transportation
- ✓Short distance to advanced medical care
Remote Expedition
- ✓Limited medical facilities
- ✓Long travel to hospital
- ✓Possible helicopter or air evacuation
The same emergency medical limit can have very different practical value in those two settings.
I would therefore give evacuation and assistance services much more attention on a remote trip.
Check Destination-Specific Official Guidance
Before selecting a policy, I also review current official travel information for the destination.
State Department travel advisories frequently tell travelers to check medical insurance, evacuation assistance, and trip cancellation protection before departure.
The objective is not to buy insurance because an advisory sounds worrying.
It is to understand whether your itinerary creates risks that the policy needs to address.
Step 4: Decide Which Financial Risks Matter Most
Travel policies can contain many benefits.
You probably do not need to treat every benefit as equally important.
I normally rank the risks.
For example:
High Priority
- ✓Emergency medical
- ✓Medical evacuation
- ✓Large non-refundable trip cost
Medium Priority
- ✓Trip interruption
- ✓Travel delay
Lower Priority for This Trip
- ✓Small baggage benefit
Your priorities could be completely different.
The important thing is to know them before comparing plans.
Do Not Let Minor Benefits Distract You From Major Risks
A policy may advertise:
- ✓Concierge service
- ✓Small baggage bonus
- ✓Travel assistance
- ✓Several minor convenience benefits
Those can be useful.
But I would not choose them over adequate protection for a serious financial risk such as:
- ✓Hospital treatment
- ✓Medical evacuation
- ✓$10,000 non-refundable vacation
Compare the largest potential losses first.
Step 5: Decide How Important Trip Cancellation Is
Cancellation coverage becomes more important as your non-refundable financial exposure increases.
For example:
Traveler A
Non-refundable cost:
$500
Traveler B
Non-refundable cost:
$9,000
Their cancellation decisions should not automatically be the same.
I would ask:
Could I comfortably lose this amount if I had to cancel for a reason insurance does not cover?
That question helps determine how much protection matters.
Standard Cancellation and CFAR Solve Different Problems
Standard trip cancellation normally works only for reasons covered by the policy.
Cancel for Any Reason, or CFAR, can provide broader flexibility but usually comes with:
- ✓Additional cost
- ✓Timing conditions
- ✓Partial reimbursement
- ✓Other eligibility requirements
NAIC’s 2026 travel-insurance guidance describes CFAR as broader protection that commonly reimburses only part of the trip cost rather than the full amount.
Do not automatically buy CFAR because it sounds more comprehensive.
First identify whether the flexibility solves a risk you genuinely care about.
Step 6: Decide How Important Medical Coverage Is
Medical risk should be evaluated separately from trip price.
A cheap vacation can still create an expensive medical emergency.
Imagine:
Trip cost:
$1,200
Emergency medical or evacuation cost:
potentially far more.
That is why I never decide medical protection based only on how much the vacation costs.
I check:
- ✓Existing health coverage abroad
- ✓Destination healthcare
- ✓Medical limit
- ✓Deductible
- ✓Primary vs secondary coverage
- ✓Evacuation limit
- ✓Pre-existing-condition rules
Medical Coverage and Evacuation Should Be Compared Separately
A policy might show:
Emergency medical: $100,000
Medical evacuation: $500,000
These are different benefits.
Emergency medical generally concerns treatment.
Evacuation concerns qualifying medical transportation.
Do not see one large number and assume it covers both.
The State Department specifically recommends considering evacuation coverage because ordinary health insurance often does not cover air ambulance transportation home.
Step 7: Consider Your Age and Health Situation
Age can affect:
- ✓Insurance price
- ✓Eligibility
- ✓Existing health coverage
- ✓Medical needs
NAIC currently identifies age among the factors that can influence travel-insurance cost.
But age alone should not determine the policy.
I would also look at:
- ✓Existing medical protection
- ✓Pre-existing-condition rules
- ✓Trip duration
- ✓Destination
- ✓Evacuation risk
A healthy 70-year-old with limited overseas health coverage may have a different insurance decision from a 35-year-old with strong employer-sponsored international coverage.
Pre-Existing Conditions Need Early Attention
If pre-existing medical conditions could affect:
- ✓Emergency treatment
- ✓Cancellation
- ✓Interruption
check those rules before choosing the policy.
Do not wait until after comparing prices.
Some policies can have waiver provisions with eligibility or purchase-timing requirements.
For this buying guide, the main rule is:
If pre-existing-condition protection matters to you, make it one of your first comparison filters, not your last.
Step 8: Check Every Important Activity
A general travel insurance policy can look suitable until you discover the main activity of your trip is restricted.
This matters for trips involving:
- ✓Skiing
- ✓Trekking
- ✓Scuba diving
- ✓Cycling
- ✓Motorbike riding
- ✓Climbing
- ✓Other higher-risk activities
Some current State Department advisories specifically warn that adventure travel and sports may not be covered by ordinary accident insurance or safety protections.
So I search the policy for the exact activity.
Do Not Ask Only “Are Sports Covered?”
Be specific.
Instead of:
“Is trekking covered?”
ask:
“Is a guided trek reaching 4,800 meters covered for emergency medical treatment and medical evacuation?”
Instead of:
“Is scuba included?”
ask:
“Is recreational scuba to my planned depth and certification level covered?”
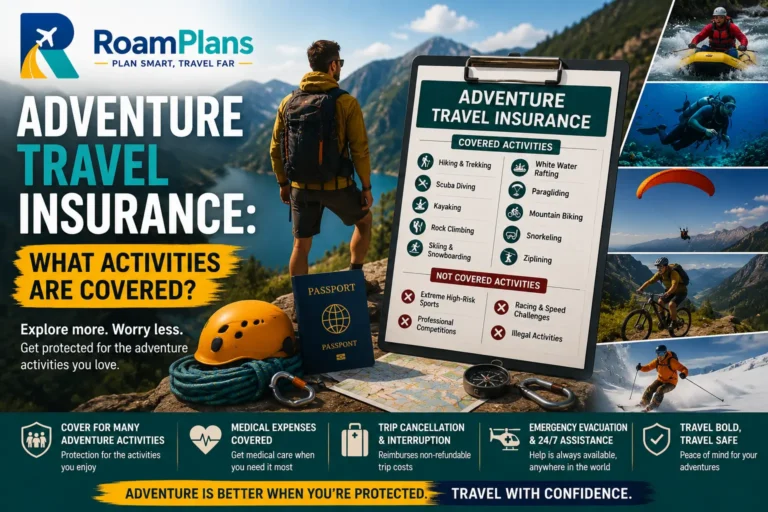
The detailed activity rules belong in Adventure Travel Insurance: What Activities Are Covered?
For policy selection, the key point is that your main trip activity should become a filter before you compare price.
Step 9: Compare Benefit Limits

Once I know which risks matter, I compare limits.
For example:
| Benefit | Plan A | Plan B |
|---|---|---|
| Emergency medical | $50,000 | $250,000 |
| Medical evacuation | $250,000 | $500,000 |
| Cancellation | $5,000 | $10,000 |
| Travel delay | $500 | $1,000 |
| Baggage | $1,500 | $2,500 |
But I do not automatically choose Plan B.
The next questions are:
- ✓Do I need the larger limits?
- ✓What exclusions apply?
- ✓Is there a higher deductible?
- ✓How much more does the policy cost?
Limits need context.
A Higher Limit Is Not Automatically Better Value
Suppose:
Plan A
Medical:
$100,000
and fits your itinerary well.
Plan B
Medical:
$1 million
but costs much more and adds protection you are unlikely to use.
The larger number does not automatically make Plan B the smarter purchase.
Insurance should protect meaningful financial exposure without encouraging you to pay for headline numbers you do not need.
Step 10: Compare Deductibles
The deductible affects how much you may have to pay yourself when an eligible claim occurs.
For example:
Plan A
Medical limit:
$250,000
Deductible:
$0
Plan B
Medical limit:
$250,000
Deductible:
$500
The headline coverage is identical.
The out-of-pocket position is not.
When comparing policies, I look at:
limit + deductible + exclusions
together.
Do Not Choose a Deductible in Isolation
A higher deductible may reduce the premium.
That can be reasonable if you are comfortable paying smaller losses yourself.
But do not choose it only because:
the premium is cheaper.
Ask:
Could I comfortably pay this deductible during an emergency abroad?
That is the more practical question.
Step 11: Read the Exclusions Before Comparing Final Price
This is where many policies that look similar begin to separate.
NAIC’s current travel-insurance guidance notes common exclusion areas can include pre-existing conditions, pregnancy and childbirth, pandemics, civil or political unrest, and certain risky activities, although individual policies differ.
I would search specifically for exclusions connected to:
- ✓My medical circumstances
- ✓My destination
- ✓My activities
- ✓My main cancellation concerns
A large benefit is not useful when the event you care about is excluded.
The Exclusion Section Can Matter More Than the Benefit Table
Comparison pages are designed to make limits easy to scan.
For example:
Medical — $250,000
Evacuation — $500,000
Cancellation — 100%
But the exclusion section answers another question:
When do those numbers stop applying?
That is why I do not make the final choice from a comparison table alone.
Step 12: Read the Definitions
Insurance words can have specific contractual meanings.
Check definitions such as:
- ✓Family member
- ✓Traveling companion
- ✓Pre-existing condition
- ✓Trip
- ✓Common carrier
- ✓Sickness
- ✓Injury
The definition can affect whether a situation qualifies.
This matters especially when you are choosing insurance around:
- ✓Family emergencies
- ✓Existing medical conditions
- ✓Shared trips
A Policy Can Look Good Until a Definition Changes the Meaning
Suppose your main cancellation concern is serious illness of a relative at home.
The cancellation benefit looks strong.
But if that relative does not meet the policy’s definition of:
family member
the coverage may not work as you expected.
That is why the buying process should include both benefits and definitions.
Step 13: Compare Price Only After Coverage Fits
Once I have narrowed the policies to ones that fit the trip, then I compare price.
NAIC’s April and June 2026 guidance says travel insurance commonly costs approximately 5%–10% of total trip price, although the actual cost varies with factors such as season, origin, destination, age, and coverage.
I use that only as broad context.
I do not use it as a target.
A policy costing 6% of the trip is not automatically good.
A policy costing 11% is not automatically bad.
What matters is the protection received for that price.
Do Not Buy Insurance Because It Falls Inside a Percentage Range
Suppose your trip costs:
$5,000
One plan costs:
$275
Another costs:
$425
The cheaper plan might be better.
Or the more expensive one might solve an important risk the cheaper plan excludes.
Compare what you receive before judging value.
Cheapest Does Not Mean Best
A cheap policy may save money today but provide:
- ✓Lower limits
- ✓Higher deductible
- ✓Narrower activity coverage
- ✓Less useful cancellation terms
If those differences matter to your trip, the cheaper premium may not represent better value.
Most Expensive Does Not Mean Best Either
The opposite mistake is assuming:
more expensive = safer.
A premium policy may include benefits you do not need.
For example, you may pay more for:
- ✓Higher cancellation limit than your trip cost
- ✓Adventure coverage for activities you will never do
- ✓Additional baggage protection when you carry little of value
Pay for risks, not prestige.
My First Policy Comparison Table
After completing the trip-risk review, I would compare policies like this:
| Question | Plan A | Plan B | Plan C |
|---|---|---|---|
| Non-refundable trip cost protected | Check | Check | Check |
| Emergency medical limit | Check | Check | Check |
| Medical deductible | Check | Check | Check |
| Medical evacuation | Check | Check | Check |
| Pre-existing-condition rules | Check | Check | Check |
| Main activity covered | Check | Check | Check |
| Cancellation risks fit | Check | Check | Check |
| Important exclusions | Check | Check | Check |
| Trip duration fits | Check | Check | Check |
| All destinations covered | Check | Check | Check |
| 24/7 assistance | Check | Check | Check |
| Premium | Check | Check | Check |
This lets me compare policies on the trip’s real risks rather than on marketing.
Do Not Score Every Feature Equally
If medical evacuation is a major concern, it should matter more than a small baggage difference.
If almost all bookings are refundable, cancellation limits may matter less.
I would mentally weight the table.
For example:
Essential
Must fit.
Useful
Helpful but negotiable.
Low Priority
Would not influence the decision much.
That creates a more realistic comparison.
My Rule for Shortlisting a Policy
Before a travel insurance plan reaches my final shortlist, I want five things to be true:
It covers the travelers and trip dates correctly.
Its major limits fit the financial risks of the trip.
My important activities and circumstances are not excluded.
I understand the deductible and main conditions.
The price makes sense compared with the protection I actually need.
Only after those five checks would I spend time comparing smaller benefits.
Step 14: Decide Between Single-Trip and Annual Travel Insurance

After I know what coverage I need, I decide whether I am protecting one trip or several trips across the year.
A single-trip policy is built around one defined journey.
An annual or multi-trip policy is designed to cover multiple eligible trips during its policy period, subject to its own trip-length, benefit, destination, and eligibility rules. Current annual-plan examples show that benefits and maximum trip lengths can differ significantly between plans, so I would never assume all annual policies work the same way.
The decision should come from your actual travel pattern.
When a Single-Trip Policy Can Make More Sense
I would give a single-trip policy stronger consideration when:
- ✓I have one major vacation planned
- ✓The trip has a high non-refundable cost
- ✓I want coverage matched closely to one itinerary
- ✓My activities are unusual
- ✓My destination creates special medical or evacuation concerns
- ✓I do not expect to travel much again that year
The advantage is that you can compare the policy against the exact:
- ✓Dates
- ✓Destination
- ✓Cost
- ✓Travelers
- ✓Activities
of that particular trip.
Example: One Expensive International Vacation
Suppose you are taking:
One 18-day international trip
with:
$10,000 in non-refundable bookings.
You do not expect another major trip during the year.
I would compare single-trip policies closely because the insurance can be selected around that particular $10,000 exposure.
An annual plan might still work, but I would not buy it simply because the word annual sounds like more coverage.
When Annual Travel Insurance Deserves Consideration
Annual insurance becomes more relevant when you expect to take several eligible trips during the year.
Current insurer products show annual policies being designed specifically for frequent travelers and multiple trips, but their benefit structures can differ from single-trip plans.
I would consider annual coverage when I expect:
- ✓Several vacations
- ✓Frequent business trips
- ✓Multiple domestic and international trips
- ✓Regular weekend travel
But I would still compare the annual plan’s actual limits against my largest and riskiest trips.
Annual Does Not Mean Unlimited Everything
This is a major point.
An annual plan may cover multiple trips while still placing limits on:
- ✓Length of each trip
- ✓Cancellation benefits
- ✓Medical benefits
- ✓Evacuation benefits
- ✓Total benefits across the year
For example, current annual products from different insurers use different maximum-trip-duration and benefit structures. Travel Guard’s current annual plan covers multiple trips and has its own stated benefit maximums, while Allianz’s annual products use different limits depending on the selected plan.
That is why I would never compare:
single-trip policy vs annual policy
using price alone.
Check Maximum Trip Duration
This is one of the first things I would look for in an annual policy.
If you normally take:
7-day trips
a trip-length restriction may not matter much.
If you are planning:
a 60-day international journey
it can become critical.
Current annual products illustrate how maximum covered trip lengths can vary by plan.
Always use the limit in the actual policy you are considering.
Check Whether Annual Benefits Reset Per Trip or Apply Across the Year
Annual policies can structure benefit limits differently.
Some may provide certain limits per trip.
Others may apply certain limits across the full policy year.
Current annual-plan examples show why this needs to be checked rather than assumed.
Ask:
“Is this benefit per trip, per person, or for the entire policy year?”
Do that for the benefits that matter most to you.
Compare Annual Coverage Against Your Most Expensive Trip
Suppose you take:
- ✓Weekend trip: $600
- ✓Europe trip: $7,000
- ✓Domestic trip: $1,200
- ✓Cruise: $5,000
An annual plan may look convenient.
But I would specifically ask:
Would its cancellation and interruption limits adequately protect the $7,000 trip?
Current Allianz guidance for its annual products similarly tells buyers to examine annual cancellation/interruption limits against the trips they expect to take.
Convenience should not cause you to underinsure your biggest trip.
My Annual vs Single-Trip Test
I ask four questions:
1. How Many Trips Will I Take?
One major trip favors a closer single-trip comparison.
Several trips make annual coverage worth comparing.
2. What Is My Most Expensive Trip?
Make sure the annual limits can handle it.
3. What Is My Longest Trip?
Make sure it fits the policy’s maximum duration.
4. Do My Trips Have Very Different Risks?
A city weekend and a remote expedition may not fit equally well under the same plan.
That last question is especially important.
Step 15: Check Your Credit-Card Travel Benefits
Before paying for a travel policy, I also check the benefits attached to the credit card used for travel bookings.
NAIC’s June 2026 consumer guidance specifically notes that some credit cards provide trip cancellation and lost-baggage benefits and recommends checking whether those benefits are enough for your needs.
That does not mean credit-card protection is bad.
It means I would treat it as existing coverage that needs to be understood.
Do Not Assume a Premium Credit Card Replaces Travel Insurance
A card may provide selected travel protections while leaving other risks less protected or unprotected.
I would check the actual card benefit guide for:
- ✓Trip cancellation
- ✓Trip interruption
- ✓Travel delay
- ✓Baggage
- ✓Rental vehicle protection
- ✓Emergency medical
- ✓Medical evacuation
Do not infer one benefit from another.
If the card advertises:
Trip Cancellation Protection
that does not automatically tell you what medical coverage exists abroad.
NAIC recommends checking the card’s actual policy and deciding whether the existing protection is sufficient.
Check How Much of the Trip Must Be Paid With the Card
Card travel benefits can have eligibility requirements.
For example, the benefit guide may require qualifying travel expenses to be paid with the eligible card.
Do not assume you qualify simply because you own the card.
Read:
- ✓Payment requirements
- ✓Eligible travelers
- ✓Covered trip definitions
- ✓Maximum benefit
- ✓Covered reasons
in the card’s current benefit guide.
Compare Card Coverage With Your Main Risks
Suppose your card provides useful protection for:
- ✓Trip cancellation
- ✓Baggage
but your biggest concern is:
- ✓Emergency medical care abroad
- ✓Medical evacuation
Then you may still have an important insurance gap.
This is why I create a simple existing coverage vs remaining gap table.
| Risk | Existing Protection | Remaining Gap |
|---|---|---|
| Cancellation | Credit card benefit | Check limit/reasons |
| Baggage | Card + homeowners | Check overlap |
| Emergency medical | Limited/none | Important gap |
| Medical evacuation | None found | Important gap |
NAIC notes that some baggage protection can overlap with homeowners policies and credit-card coverage, which is another reason to identify existing protection before buying more.
Do Not Pay for Duplicate Coverage Without Understanding It
Overlap is not automatically bad.
But I want to know when it exists.
For example, baggage could potentially involve:
- ✓Airline reimbursement
- ✓Credit-card protection
- ✓Homeowners insurance
- ✓Travel insurance
NAIC specifically describes baggage insurance as commonly secondary and notes that travelers may already have some protection through homeowners insurance or credit cards.
That should affect how much weight you give baggage coverage when comparing travel policies.
Step 16: Understand Primary vs Secondary Coverage
This term matters because it can affect how a claim works.
NAIC currently describes travel medical insurance and baggage coverage as commonly secondary types of protection.
In practical terms, secondary coverage may require another applicable source of insurance to respond first.
That can affect:
- ✓Claim paperwork
- ✓Reimbursement timing
- ✓Which insurer you contact first
For buying purposes, I simply want to know which structure I am choosing.
Why Primary vs Secondary Can Affect Convenience
Imagine you receive overseas medical treatment.
With one policy structure, the travel insurer may handle an eligible claim directly under its terms.
With a secondary arrangement, you may first need a decision from another health insurer.
Neither structure should automatically be labeled good or bad.
But the claim process can be different.
If two policies otherwise look similar, I would consider this practical difference.
Do Not Pay a Large Premium Difference Just for One Label Without Reading the Terms
A policy marked:
Primary
may look easier to use.
But I would still compare:
- ✓Limit
- ✓Deductible
- ✓Exclusions
- ✓Destination coverage
- ✓Assistance
- ✓Price
The label alone should not decide the policy.
Step 17: Consider Family and Group Structure
If more than one person is traveling, I check whether the policy works for the group as booked, not simply whether everyone can be added.
Questions include:
- ✓Does each traveler meet eligibility requirements?
- ✓Are benefit limits per person or shared?
- ✓Are children included?
- ✓Do all travelers need the same policy?
- ✓Are trip costs shared?
- ✓Are family definitions important to cancellation coverage?
This is where a general buying decision can become more complicated.
One Policy May Be Convenient for a Family
A family policy can make administration simpler when:
- ✓Everyone travels on the same dates
- ✓Everyone has similar coverage needs
- ✓Children meet eligibility rules
But if one traveler has very different needs, I would compare separate protection as well.
For the family-specific details, use Family Travel Insurance Guide: Coverage for Parents and Children instead of turning this buying guide into a second family-insurance article.
Groups Should Check Who Is Actually Insured
A group of friends traveling together is not automatically the same as a family.
If five friends book one vacation rental, make sure each traveler who expects insurance protection is actually covered according to the policy.
Do not assume:
same itinerary = same insurance.
Step 18: Look for 24/7 Emergency Assistance
For international travel, I consider the assistance service an important practical feature.
The State Department specifically recommends finding out whether the insurance company has a 24-hour help line during the trip.
That can matter when you need help with:
- ✓Finding medical care
- ✓Medical transportation
- ✓Emergency coordination
- ✓Travel documents
- ✓Other assistance services
NAIC notes that travel assistance services can include medical referrals, translation assistance, and help with lost luggage or travel documents, although those assistance services may be separate from the insurance benefits themselves.
Assistance and Insurance Are Not the Same Thing
This is important when comparing plans.
A policy can advertise:
24/7 assistance
but assistance does not automatically mean:
every expense the assistance team helps arrange will be reimbursed.
NAIC distinguishes travel assistance services from insurance products and notes that travel packages can bundle insurance and non-insurance services together.
So I check both:
What help will they provide?
and
Which expenses does the insurance actually cover?
Test Whether the Emergency Information Is Easy to Find
Before buying, I look for:
- ✓Emergency phone number
- ✓International contact
- ✓Assistance details
- ✓Claims process
If these are difficult to locate before purchase, I would want clarity before relying on the policy abroad.
The State Department’s current buying checklist explicitly tells international travelers to look for 24-hour assistance and to confirm destination, trip length, emergency medical care, medical transportation, and planned activities.
Step 19: Check Whether the Policy Covers Every Destination
If a trip includes several countries, I check the entire itinerary.
For example:
France → Switzerland → Italy → Greece
Do not verify only France because it is your first destination.
The State Department recommends making sure travel insurance is valid in the countries you plan to visit.
This becomes especially important for:
- ✓Multi-country trips
- ✓Cruises
- ✓Long stopovers
- ✓Remote areas
- ✓Destinations with special restrictions
Check the Full Trip Length Too
The State Department also specifically recommends checking whether the policy covers the length of your trip.
This is easy to overlook when:
- ✓Arriving one day early
- ✓Staying after a tour ends
- ✓Taking a long stopover
- ✓Extending the trip later
The policy dates should match the trip you actually intend to take.
Step 20: Check Current Medical Conditions and Activities
The State Department’s current insurance checklist tells travelers to review whether a policy fits current medical conditions for themselves and family members and whether it covers planned activities.
These should be filters, not afterthoughts.
If your trip includes a major activity or a health-related coverage concern, remove policies that clearly do not fit before you begin comparing minor features.
Step 21: Check the Insurance Company and Seller
Once I find a policy that appears to fit, I also want to know who is actually providing the insurance.
For U.S. consumers, state Departments of Insurance regulate insurers and insurance professionals. NAIC says state regulators can help consumers verify whether companies, agents, and adjusters are licensed, and some state departments provide online verification tools.
This is useful because the brand selling the travel product is not always the same company underwriting the insurance.
Find the Actual Insurance Provider
Before purchasing, look for information such as:
- ✓Insurance company
- ✓Underwriter
- ✓Producer or seller
- ✓State-specific policy form
Do not rely only on the booking website’s brand name.
Travel insurance products can also be bundled with non-insurance products, which NAIC says are regulated differently.
Knowing what you are actually buying matters.
Use Your State Insurance Department When You Need Verification
For U.S. buyers, NAIC provides a directory of state insurance departments, and these departments can help consumers with insurance questions and complaints.
NAIC also says state insurance departments can help with:
- ✓Understanding policy terms
- ✓Checking licences
- ✓Coverage questions
- ✓Consumer complaints
depending on the jurisdiction.
This is more useful than trusting an unknown website that simply labels an insurer:
Top Rated
without explaining why.
Do Not Choose Only From Online Star Ratings
Customer reviews can provide information about people’s experiences.
But I would not make a financial coverage decision based only on:
- ✓Five-star score
- ✓Influencer recommendation
- ✓Affiliate ranking
- ✓“Best travel insurance” badge
Instead, I prioritize:
- ✓Policy fit
- ✓Actual wording
- ✓Limits
- ✓Exclusions
- ✓Insurer/provider verification
- ✓Price
Reviews can be supporting information after those checks.
Step 22: Understand What You Are Buying at Checkout
Flight, cruise, hotel, and tour booking pages often offer travel protection during checkout.
NAIC notes that travel insurance is frequently bundled with non-insurance products such as cancellation fee waivers and travel assistance services.
Do not click:
Add protection
without checking whether the product is:
- ✓Insurance
- ✓Cancellation waiver
- ✓Assistance service
- ✓Package containing several products
Those are not automatically interchangeable.
A Cancellation Waiver Is Not Necessarily Travel Insurance
NAIC specifically distinguishes cancellation fee waivers from insurance products.
A supplier waiver may help with certain fees or cancellations under its own terms.
It should not automatically be assumed to provide:
- ✓Emergency medical insurance
- ✓Medical evacuation
- ✓Baggage insurance
- ✓Other travel insurance benefits
Read what is actually being sold.
Compare Checkout Insurance Against Independent Options
I would not automatically reject the insurance offered with a booking.
But I also would not automatically accept it.
I would compare it with other suitable policies using the same criteria:
- ✓Main risks
- ✓Limits
- ✓Exclusions
- ✓Deductible
- ✓Price
The fact that a policy appears beside your airline ticket does not prove it is the best fit for your full trip.
Step 23: Do Not Wait Until the Last Minute if Time-Sensitive Benefits Matter
Timing can affect some travel-insurance options.
NAIC’s June 2026 guidance says buying early may help and warns that if you wait until a storm is already named, claims connected with that known storm are unlikely to be covered by a newly purchased policy.
CFAR is another example where timing commonly matters.
NAIC says CFAR generally has purchase deadlines and other eligibility conditions.
So I compare insurance soon after meaningful trip costs become non-refundable when these benefits matter to me.
Buying Early Does Not Mean Buying the First Policy You See
My process is:
- ✓Understand trip costs.
- ✓Identify major risks.
- ✓Check existing insurance.
- ✓Compare appropriate policies.
- ✓Check time-sensitive benefits.
- ✓Read exclusions.
- ✓Purchase once the policy fits.
This prevents two opposite mistakes:
buying too quickly
and
waiting until useful options have disappeared.
Step 24: Compare the Actual Policy, Not Just the Quote Page
A quote page is useful for comparing:
- ✓Price
- ✓Main limits
- ✓Headline benefits
But my final decision comes from the policy documents.
NAIC’s current guidance says each policy sets its own limits and specifies the situations it will and will not cover, and consumers should ask the company exactly what the policy covers before purchasing.
That is the document I trust over marketing summaries.
Search the Policy for Your Personal Risk Words
Instead of reading hundreds of pages randomly, I search for terms relevant to my trip.
Examples:
pre-existing
trekking
skiing
pregnancy
family member
evacuation
deductible
cancellation
motorcycle
This is faster and more useful than reading every section with equal attention.
Step 25: Compare Policies Side by Side

Once I have narrowed my options, I create one final table.
| Selection Factor | Plan A | Plan B | Plan C |
|---|---|---|---|
| Premium | Check | Check | Check |
| Trip cancellation fit | Check | Check | Check |
| Emergency medical | Check | Check | Check |
| Medical deductible | Check | Check | Check |
| Medical evacuation | Check | Check | Check |
| Main activity covered | Check | Check | Check |
| Pre-existing rules fit | Check | Check | Check |
| Important exclusions | Check | Check | Check |
| Primary/secondary | Check | Check | Check |
| Trip duration | Check | Check | Check |
| All countries covered | Check | Check | Check |
| 24/7 assistance | Check | Check | Check |
| Existing coverage overlap | Check | Check | Check |
| Insurer verified | Check | Check | Check |
Then I remove plans that fail an essential requirement.
Use Pass/Fail for Essential Coverage
This is better than giving every feature a score.
Suppose high-altitude trekking is the main reason for the trip.
If Plan A excludes the trek, it fails.
It does not matter that Plan A has:
- ✓Better baggage coverage
- ✓Lower premium
- ✓Larger travel-delay benefit
The main trip risk is not solved.
Use:
Essential = Pass or Fail
before comparing nice-to-have features.
Then Compare Value Among the Policies That Pass
Once all remaining plans meet the essential requirements, compare:
- ✓Premium
- ✓Deductible
- ✓Limits
- ✓Convenience
- ✓Secondary benefits
This creates a much cleaner decision.
You are no longer asking:
“Which of 20 policies is best?”
You are asking:
“Which of these three policies that actually fit my trip gives me the best balance of protection and cost?”
A Practical Example
Suppose you are planning:
- ✓14-day trip to Japan
- ✓Two travelers
- ✓$6,000 non-refundable trip cost
- ✓Existing health insurance has limited overseas protection
- ✓No adventure sports
You shortlist three policies.
Plan A
Lowest premiumLow medical limitGood cancellation coverage
Plan B
Moderate premiumStronger medical and evacuation protectionGood cancellation coverage
Plan C
Highest premiumVery high limitsAdventure benefits you do not need
I would probably investigate Plan B most closely.
Not because it is the middle price.
Because it appears to match the actual risks better.
Then I would read the exclusions before making the final choice.
Another Example: Mostly Refundable Trip
Suppose:
- ✓$4,000 total trip
- ✓Only $500 is non-refundable
- ✓Strong existing overseas health coverage
- ✓City destinations
- ✓No unusual activities
Your insurance priorities may be much smaller.
A premium comprehensive policy may provide more protection than you need.
This is why there is no universal best plan.
Another Example: Remote Adventure Trip
Suppose:
- ✓$2,500 trip cost
- ✓Remote trekking
- ✓Limited local healthcare
- ✓Weak existing overseas medical coverage
Cancellation exposure is relatively modest.
But medical and evacuation exposure could be substantial.
The State Department strongly recommends medical evacuation insurance for higher-risk destinations or places with limited medical care.
In this case, I would prioritize:
- ✓Activity eligibility
- ✓Medical limit
- ✓Evacuation
- ✓Assistance
over having an unusually large cancellation benefit.
Another Example: Frequent Traveler
Suppose you expect:
- ✓Four domestic trips
- ✓Two international trips
- ✓Several short business trips
An annual policy may deserve comparison because current annual products are specifically structured to cover multiple eligible trips.
But I would still check:
- ✓Most expensive trip
- ✓Longest trip
- ✓Annual benefit limits
- ✓International medical coverage
before deciding it is better than separate single-trip plans.
My Final Shortlisting Rule
Before I consider a policy a serious candidate, I want to be able to say:
It covers my destinations and trip length.
Its limits fit my biggest financial risks.
My important activities and circumstances fit the policy.
I understand what existing insurance will pay first.
I know who the insurer is.
I know how to reach assistance during the trip.
I have read the important exclusions.
Only then do I compare the final premium.
That order helps keep the decision focused on protection first and price second.
Step 26: Do a Final Policy Check Before Paying

Before I buy, I stop comparing for a moment and check whether the policy actually matches the trip I am planning.
I want to confirm:
- ✓Correct travelers
- ✓Correct travel dates
- ✓Correct destinations
- ✓Correct trip cost
- ✓Important activities covered
- ✓Medical limits understood
- ✓Evacuation benefit understood
- ✓Cancellation protection appropriate
- ✓Main exclusions reviewed
- ✓Deductibles understood
The U.S. State Department recommends reviewing travel insurance carefully before purchase so you understand what the policy does and does not cover, especially medical care and medical evacuation for international trips.
Check That Every Traveler Is Actually Included
Do not assume that because you entered:
2 travelers
everyone who needs insurance is properly covered.
Verify:
- ✓Full names
- ✓Ages
- ✓Relationships where relevant
- ✓Residency requirements
- ✓Trip dates
This matters particularly for:
- ✓Families
- ✓Children
- ✓Older travelers
- ✓Groups
If one person’s situation is significantly different, compare whether separate insurance would make more sense.
Check the Insured Trip Cost One More Time
Trip costs can change while you are planning.
Maybe you initially booked:
$2,500
but later added:
- ✓Another hotel
- ✓Cruise
- ✓Tour
- ✓Non-refundable flight
Now the amount at risk may be:
$5,500
If the policy requires you to declare or insure certain trip costs, update the figure according to the insurer’s instructions.
Do not assume the original quote remains appropriate after major booking changes.
Separate Refundable and Non-Refundable Costs
I would make one final list.
Refundable
Money I expect the supplier to return if I cancel within its rules.
Non-Refundable
Money I could genuinely lose.
This keeps me from buying cancellation coverage based on an inflated trip-cost number.
Check Your Biggest Financial Risk
Every trip has a different priority.
For one traveler, it may be:
$12,000 in non-refundable bookings.
For another:
international medical treatment.
For another:
medical evacuation from a remote area.
Your final policy should perform well against the largest realistic loss you are trying to protect.
Do not let several small benefits distract you from that.
Step 27: Check Medical Protection One Final Time
For international travel, I would confirm what medical protection I already have before relying on a new travel policy.
The State Department advises travelers to understand what their existing health insurance covers outside the United States and notes that many plans do not cover the cost of bringing a traveler back to the United States by air ambulance.
Ask:
- ✓Does my normal health insurance work abroad?
- ✓What gap remains?
- ✓Does this travel policy fill that gap?
- ✓Is medical evacuation separate?
- ✓What deductible applies?
If you use Original Medicare, Medicare’s current guidance says coverage outside the United States is generally very limited, with specific exceptions.
Do not buy a travel medical benefit without understanding what it is supplementing.
Step 28: Check Medical Evacuation Separately
Medical treatment and evacuation are different financial risks.
The State Department strongly recommends medical evacuation insurance for higher-risk locations or destinations where adequate medical care may be limited.
I would check:
- ✓Evacuation limit
- ✓Medical necessity rules
- ✓Authorization
- ✓Destination of transport
- ✓Repatriation where relevant
A large medical-treatment limit does not automatically tell you how evacuation works.
Check Whether Your Destination Changes the Priority
A normal city break and a remote expedition should not automatically lead to the same insurance decision.
For remote or medically limited areas, I would place more weight on:
- ✓Evacuation
- ✓Emergency assistance
- ✓Medical protection
The State Department’s current health guidance says air ambulance transport back to the United States can cost roughly $20,000 to $200,000, depending on location and medical condition.
That is why a relatively inexpensive trip can still create a large medical financial risk.
Step 29: Check Your Main Cancellation Risk
I would ask:
What is the most realistic reason I might need to cancel this trip?
Then check whether that reason fits the policy.
Standard cancellation insurance does not mean you can cancel for any personal reason.
NAIC’s current travel-insurance guidance distinguishes standard cancellation coverage from Cancel for Any Reason protection and says CFAR generally provides only partial reimbursement, typically around 50%–75% of total trip price.
If flexibility matters more than traditional covered reasons, compare CFAR carefully.
If it does not, do not automatically pay extra for it.
Step 30: Check the Activities That Define the Trip
If an activity is one of the main reasons you are traveling, it should be part of the final insurance check.
Examples include:
- ✓Skiing
- ✓Trekking
- ✓Scuba diving
- ✓Cycling
- ✓Mountaineering
- ✓Motorbike riding
NAIC warns that some travel medical evacuation policies may not cover activities an insurer considers dangerous.
So if the activity is essential to the trip, I treat it as:
Pass or fail.
If the policy clearly excludes the activity, I remove it from my shortlist.
The detailed activity analysis belongs in Adventure Travel Insurance: What Activities Are Covered?
Step 31: Check the Exclusions That Matter to You
You do not need to memorize every exclusion.
Focus first on exclusions connected to your own circumstances.
For example:
Medical
- ✓Pre-existing conditions
Activities
- ✓Adventure or higher-risk sports
Destination
- ✓Relevant restricted events or circumstances
Cancellation
- ✓Reasons you are personally concerned about
NAIC advises travelers to review pre-existing-condition rules and warns that medical evacuation coverage may exclude certain dangerous activities.
An exclusion that affects someone else’s trip may not matter to you.
One that affects your main trip activity can matter enormously.
Step 32: Decide Whether You Can Comfortably Pay the Deductible
A deductible is not just a number used to compare premiums.
It represents money you may need to pay yourself.
Suppose:
Policy A
Lower premium$1,000 deductible
Policy B
Higher premium$100 deductible
The cheaper premium may still be sensible if you can comfortably handle the larger deductible.
But do not choose the deductible without considering your emergency finances.
Step 33: Check How You Would Actually Use the Policy
Before purchasing, imagine:
Something goes wrong tonight while I am overseas.
Can you answer:
- ✓Who do I call?
- ✓Is there 24/7 assistance?
- ✓Where is the emergency number?
- ✓Will I need authorization?
- ✓How would I open a claim?
Insurance that looks strong on paper should also be practical to use.
The State Department encourages travelers to review medical and evacuation protection before departure, not after an emergency occurs.
Step 34: Read the Claims Instructions Before Buying
You do not need to study every claim form in detail.
But I like to know:
- ✓How claims are submitted
- ✓Whether there is an online portal
- ✓What basic documentation is required
- ✓Whether overseas medical expenses may require other insurance information
This gives me an idea of how the policy works after something goes wrong.
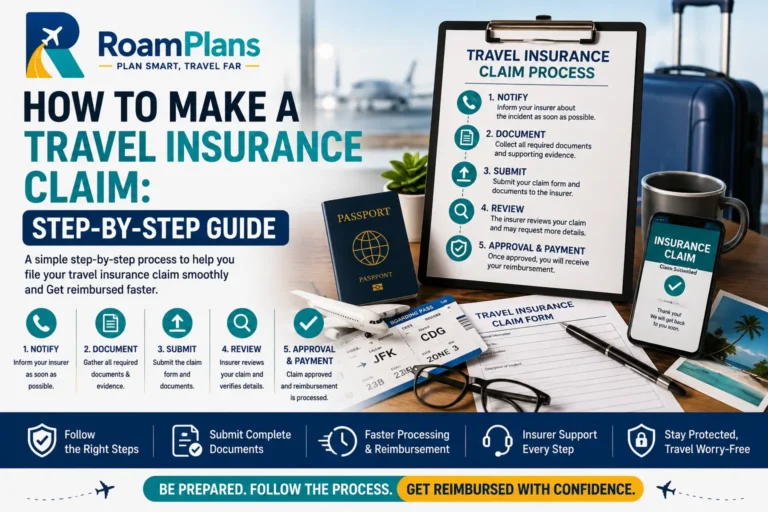
For the full process, use How to Make a Travel Insurance Claim: Step-by-Step Guide.
Step 35: Decide Whether the Price Matches the Protection
Once the policy passes the important coverage checks, then I compare price.
I ask:
What meaningful protection am I receiving for the extra premium?
Suppose:
Plan A — $180
Fits all essential risks.
Plan B — $260
Adds larger baggage and delay limits.
Plan C — $390
Adds adventure protection you do not need.
If Plan A already solves the risks you care about, paying more may provide little practical value.
But if Plan B solves an important medical or cancellation gap, the additional premium can be more meaningful.
Avoid the “More Benefits Must Be Better” Trap
Insurance comparison pages can make it easy to count features.
For example:
Plan A — 12 benefits
Plan B — 18 benefits
That does not tell you which policy is better.
Maybe the six extra benefits have little relevance to your trip.
I would rather have:
fewer useful benefits
than
many benefits that do not address my real financial risks.
Avoid the “Highest Limit Wins” Trap
A plan with:
$1 million medical coverage
is not automatically better than one with:
$250,000
if the larger-limit plan excludes the activity you intend to do or has other terms that make it a poor fit.
Compare:
limit + eligibility + exclusion + deductible
together.
Avoid the “Cheapest Policy Wins” Trap
A low premium can be attractive.
But if the cheaper policy leaves your most important risk exposed, the savings may not represent good value.
For example:
Saving:
$70
on the premium
may be less important than properly addressing a large:
medical, evacuation, or non-refundable trip risk.
Avoid the “Most Expensive Policy Must Be Safest” Trap
Price is not a quality score.
A more expensive plan may simply include:
- ✓Higher limits
- ✓More optional benefits
- ✓Coverage designed for risks you do not have
The right policy should fit the trip, not simply cost the most.
Common Travel Insurance Buying Mistakes
Mistake 1: Buying Before Understanding the Trip
Know the destinations, costs, travelers, and activities first.
Mistake 2: Looking Only at Total Trip Cost
Separate refundable and non-refundable expenses.
Mistake 3: Assuming Existing Health Insurance Works Abroad
Verify it directly. The State Department recommends checking international health coverage before departure.
Mistake 4: Forgetting Medical Evacuation
Treatment and evacuation are separate risks.
Mistake 5: Buying the Highest Limits Automatically
Higher is not always better value.
Mistake 6: Ignoring Deductibles
Know what you may need to pay yourself.
Mistake 7: Ignoring Activity Exclusions
An important adventure can change the whole insurance decision.
Mistake 8: Assuming All Cancellation Is Covered
Check the actual covered reasons.
Mistake 9: Buying CFAR Without Understanding Partial Reimbursement
NAIC says CFAR typically reimburses only part of the total trip price.
Mistake 10: Assuming Credit-Card Protection Is Enough
Compare its benefits with your remaining gaps.
Mistake 11: Buying Annual Coverage Without Checking Trip-Length Limits
Annual does not necessarily mean every trip of any duration fits.
Mistake 12: Choosing Insurance Only From Reviews
Policy wording matters more than popularity.
Mistake 13: Not Reading Definitions
Terms such as family member or pre-existing condition can materially affect coverage.
Mistake 14: Buying From Checkout Without Checking the Product
Confirm whether you are buying actual insurance, a cancellation waiver, assistance services, or a package containing several products.
Mistake 15: Waiting Until a Known Problem Exists
Insurance is designed around future uncertainty. Check time-sensitive benefits early when they matter.
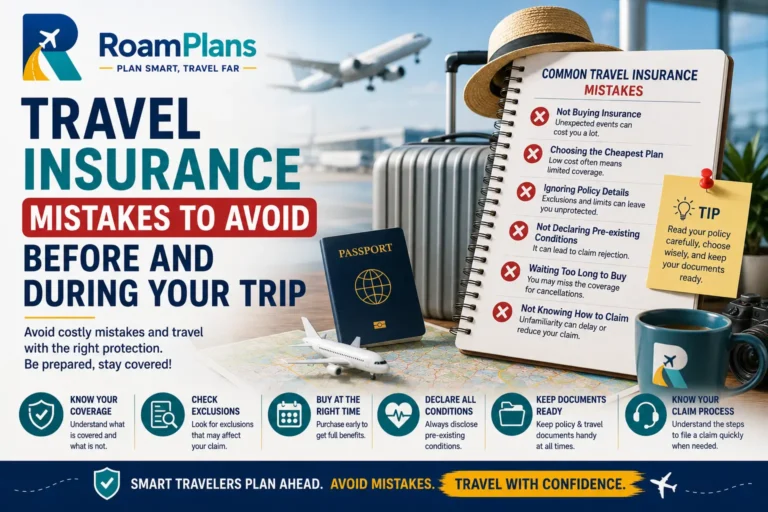
The wider behavior and policy errors travelers make are covered in Travel Insurance Mistakes to Avoid Before and During Your Trip.
My 10-Step Travel Insurance Selection Method
If I needed to choose a policy quickly, I would use this process.
1. Calculate Non-Refundable Cost
How much money can you really lose?
2. Check Existing Insurance
Especially overseas medical protection.
3. Identify the Three Biggest Risks
Do not try to insure everything equally.
4. Check the Destination
Especially healthcare access and remoteness.
5. Check Medical and Evacuation
Treat them separately.
6. Check Main Activities
Remove policies that fail an essential activity.
7. Compare Limits and Deductibles
Read both together.
8. Read Important Exclusions
Focus on those relevant to your trip.
9. Check Assistance and Claims Access
Know how you would use the policy.
10. Compare Price Among the Policies That Still Fit
Price becomes the final filter, not the first.
A Simple “Must Have / Nice to Have” Method
Another easy way to choose is to divide benefits into two groups.
Must Have
These are requirements the policy cannot fail.
For example:
- ✓International medical coverage
- ✓Medical evacuation
- ✓$6,000 cancellation protection
- ✓Skiing coverage
Nice to Have
These could improve the policy but would not determine the purchase.
For example:
- ✓Higher baggage limit
- ✓Larger delay benefit
- ✓Extra assistance service
A policy missing a must have should usually leave your shortlist even if it has many nice extras.
Example: First-Time International Traveler
Imagine:
- ✓10-day Europe trip
- ✓$3,500 non-refundable cost
- ✓Existing health insurance has limited overseas protection
- ✓No adventure activities
I would prioritize:
- ✓Emergency medical
- ✓Medical evacuation
- ✓Appropriate cancellation protection
- ✓Reasonable deductible
- ✓24/7 assistance
I would probably give less weight to unusually high adventure or equipment benefits.
Example: Older International Traveler
Imagine:
- ✓Traveler aged 70
- ✓International vacation
- ✓Original Medicare
- ✓$6,000 prepaid trip
Medicare says Original Medicare usually does not cover healthcare outside the United States except in limited circumstances.
So I would give particular attention to:
- ✓Overseas medical protection
- ✓Evacuation
- ✓Pre-existing-condition rules
- ✓Cancellation exposure
rather than simply choosing the policy marketed for seniors.
Example: Family Vacation
Imagine:
- ✓Two parents
- ✓Two children
- ✓$9,000 trip
- ✓Shared accommodation
- ✓Several prepaid bookings
I would check:
- ✓Every traveler eligible
- ✓Limits per person or per policy
- ✓Child eligibility
- ✓Shared cancellation costs
- ✓Medical and evacuation protection
The detailed family-specific issues belong in Family Travel Insurance Guide: Coverage for Parents and Children.
Example: Adventure Trip
Imagine:
- ✓$2,000 trip
- ✓High-altitude trekking
- ✓Remote medical access
The small trip cost may make cancellation less important.
But the medical and evacuation risks can still be significant.
In that situation, I would prioritize:
- ✓Exact activity coverage
- ✓Altitude limits
- ✓Medical protection
- ✓Rescue/evacuation terms
- ✓Emergency assistance
rather than choosing based on the largest cancellation limit.
Example: Frequent Traveler
Imagine you expect six trips over the year.
Annual insurance may be convenient.
But before buying, I would check:
- ✓Longest trip
- ✓Most expensive trip
- ✓International medical protection
- ✓Benefit structure across the year
Then compare the annual premium with suitable single-trip policies.
Travel Insurance Selection Scorecard
Before buying, I would want this table to look clear:
| Selection Question | Result |
|---|---|
| All travelers eligible? | Yes / No |
| All destinations covered? | Yes / No |
| Full trip duration covered? | Yes / No |
| Non-refundable cost appropriately protected? | Yes / No |
| Medical coverage fits trip? | Yes / No |
| Evacuation fits destination? | Yes / No |
| Main activity covered? | Yes / No |
| Pre-existing-condition rules acceptable? | Yes / No |
| Deductible affordable? | Yes / No |
| Major exclusions understood? | Yes / No |
| Existing insurance overlap checked? | Yes / No |
| 24/7 assistance available? | Yes / No |
| Policy wording reviewed? | Yes / No |
| Premium reasonable for protection? | Yes / No |
If an essential answer is No, I would normally keep comparing.
Final Travel Insurance Buying Checklist
Your Trip
- ✓Destination confirmed
- ✓Trip dates confirmed
- ✓Every traveler listed
- ✓Total trip cost calculated
- ✓Non-refundable cost calculated
Existing Protection
- ✓Health insurance checked abroad
- ✓Medicare-related coverage checked where relevant
- ✓Credit-card benefits checked
- ✓Supplier refund protection checked
- ✓Other existing insurance checked
Medical
- ✓Emergency medical limit reviewed
- ✓Deductible reviewed
- ✓Primary/secondary status checked where relevant
- ✓Pre-existing-condition rules reviewed
Evacuation
- ✓Medical evacuation limit checked
- ✓Authorization rules checked
- ✓Remote-destination needs considered
- ✓Repatriation wording checked where important
Cancellation
- ✓Main cancellation risks identified
- ✓Covered reasons checked
- ✓Cancellation maximum checked
- ✓CFAR considered only if useful
- ✓CFAR timing and reimbursement checked where relevant
Activities
- ✓Every major activity checked
- ✓Adventure exclusions reviewed
- ✓Altitude/depth conditions checked where relevant
- ✓Competition rules checked where relevant
Policy Structure
- ✓Single-trip vs annual compared
- ✓Maximum trip duration checked
- ✓Annual limits checked where relevant
- ✓Family/group structure checked
Policy Terms
- ✓Main exclusions read
- ✓Definitions reviewed
- ✓Deductibles understood
- ✓Benefit limits understood
- ✓Policy dates correct
Practical Use
- ✓24/7 assistance checked
- ✓Emergency contact easy to find
- ✓Claim method reviewed
- ✓Policy can be stored offline
Final Value
- ✓Cheapest suitable plan identified
- ✓More expensive options compared for meaningful differences
- ✓Unnecessary benefits identified
- ✓Final premium fits budget
- ✓Essential risks pass the policy check
Frequently Asked Questions
Start with your trip rather than the insurer. Calculate your non-refundable costs, check existing medical and credit-card protection, identify your biggest risks, compare appropriate policy limits and deductibles, read the exclusions, and then compare price among the policies that fit.
Important areas can include trip cancellation, emergency medical coverage, medical evacuation, deductibles, exclusions, destination eligibility, activity coverage, assistance services, and claim procedures. Which benefits matter most depends on your trip.
There is no universal amount. Match cancellation coverage to relevant prepaid financial exposure and compare medical and evacuation protection with your existing insurance, destination, activities, and personal risk.
Not automatically. A higher limit should be considered alongside deductibles, exclusions, existing medical protection, destination, and price.
Not necessarily. A cheaper policy can be good value if it covers your essential risks. It becomes poor value when the lower premium comes with gaps that matter to your trip.
Not automatically. Higher premiums can reflect larger limits or additional benefits that may not be important to your trip.
Cancellation protection may matter less when most expenses are refundable, but medical, evacuation, delay, or other travel risks can still exist.
It depends on your existing coverage. The State Department recommends checking what your health insurance covers overseas and considering additional medical and evacuation protection where gaps remain.
Original Medicare usually does not cover healthcare outside the United States except in limited situations.
It can be particularly important for remote or medically limited destinations. The State Department strongly recommends it for areas with higher risk or limited medical care.
Only if the additional flexibility is useful to you and the price and conditions make sense. NAIC says CFAR generally provides partial reimbursement rather than a full refund.
Single-trip coverage can fit one specific journey well. Annual insurance may be useful for frequent travelers, but you still need to check trip-length limits, annual or per-trip benefit limits, and whether your largest trip fits.
Sometimes it may cover useful parts of your risk, but you need to compare the actual card benefits with your medical, evacuation, cancellation, baggage, and delay needs before deciding whether additional insurance is necessary.
You can consider it, but compare what is actually being sold against other suitable options. A booking add-on can be insurance, a cancellation waiver, assistance services, or a bundled product.
Reviews can provide supporting information, but policy wording, limits, exclusions, eligibility, insurer identity, and price should carry more weight.
Focus on exclusions relevant to your trip, such as pre-existing conditions, important activities, destination-specific risks, and cancellation reasons you care about.
It depends on the policy. NAIC warns that some policies can exclude activities an insurer considers dangerous.
It can be useful to compare it soon after meaningful trip payments become non-refundable, especially if time-sensitive benefits such as certain cancellation options matter.
Compare the policies against the same trip-risk list: medical protection, evacuation, cancellation, activities, exclusions, deductible, destination, duration, assistance, and price.
Whether the policy meaningfully protects the biggest financial risks of your specific trip under terms and exclusions you understand.
Use comparison tools for shortlisting, but review the actual policy before purchasing. The State Department advises travelers to review insurance carefully to understand what it does and does not cover.
Final Thoughts
In short, The best travel insurance is not the cheapest, most expensive, or most feature-heavy policy; it is the one that fits your trip cost, destination, existing protection, medical and evacuation risks, planned activities, and cancellation exposure under terms you understand and a price you are comfortable paying.
Adnan Ahmed
RoamPlans AuthorTravel Planning Researcher & Editor
Adnan Ahmed is the travel planning researcher and editor behind RoamPlans. He creates clear, practical guides to help travelers compare destinations, plan routes, estimate costs, and avoid common trip-planning mistakes. His work combines careful source research, official travel information, and regular content reviews to keep each guide useful and current.
- ✓Destination Research
- ✓Budget Planning
- ✓Route Planning
- ✓Beginner Travel Guides
Turn This Guide into a Practical Trip Plan
Use the recommended Airline Baggage Allowance Checker or explore more free RoamPlans tools.